Why Tax Benefits of Foreclosure Investing Depend on Your Exit
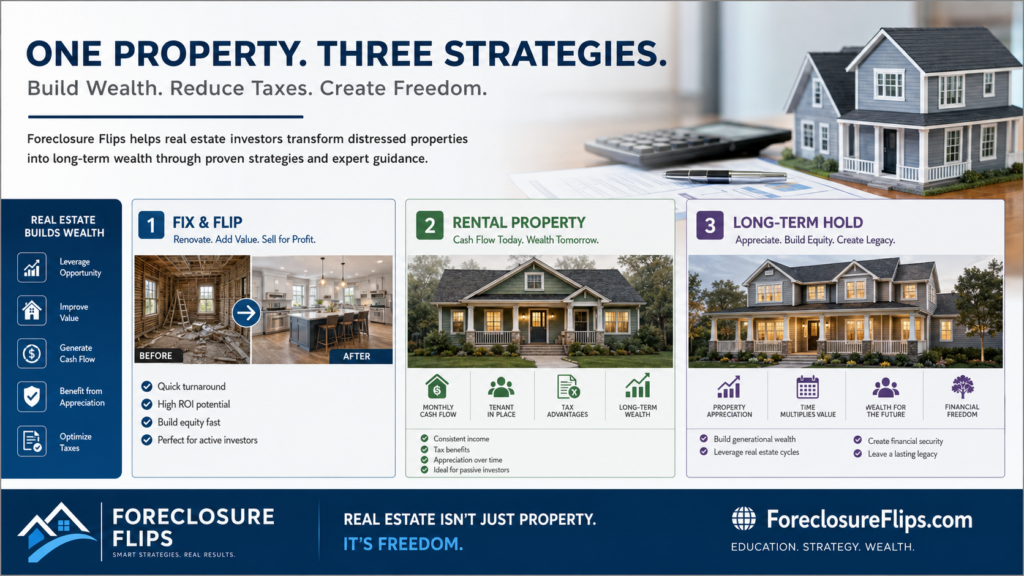
Buy a foreclosure for $180,000, put $40,000 into it, and the tax result can change sharply depending on what you do next.
Sell after the rehab, and the profit may be treated like business income. Keep the same property as a rental, and depreciation, operating deductions, passive-loss rules, cost segregation, and a future 1031 exchange can enter the picture.
That is why the tax benefits of foreclosure investing depend heavily on your exit strategy.
The useful question is not simply, “What can I deduct?” It is, “How will this property be treated if I flip it, rent it, refinance it, or hold it long term?”
Stay Ahead of the Next Deal
Markets move quickly, and good foreclosure opportunities often require fast analysis. Subscribe to our twice-weekly newsletter for investor-focused tips, tools, and market insights designed to help you make better decisions.
Your Exit Strategy Starts the Tax Analysis
A foreclosure discount does not create a special federal tax category. Federal tax treatment generally depends on how you use the property after you buy it.
A house purchased mainly to renovate and sell to customers may be treated as property held for sale in a business. By contrast, a house that you rehab, place in service, and operate as a rental can produce a different set of deductions and eventual sale rules.
That difference reaches several parts of the deal:
- Whether you depreciate the property
- How rehab costs are treated
- Whether rental losses can offset other income
- Whether a 1031 exchange may be available
- How profit is taxed when you sell
- Whether a refinance lets you access equity without triggering a sale
For foreclosure investors, this is one reason to decide the likely exit before closing. You may still change plans later, but tax planning is easier when your records, financing, and property use match what you actually intend to do.
A Foreclosure Rental Can Create Annual Deductions
Once a renovated foreclosure is placed in service as a rental, the tax picture changes.
Residential rental buildings are generally depreciated over 27.5 years under the straight-line method. Land is not depreciable. The IRS rental-property guidance explains the basic rules for depreciation, repairs, improvements, and common rental expenses.
Suppose you buy an REO for $180,000, allocate $35,000 of the price to land, and complete capital improvements before placing the house in service.
The building and capitalized improvement basis can then generate depreciation deductions over time. That can leave a rental with positive cash flow but lower taxable income.
Mortgage interest and operating costs matter too
Rental income is not taxed without regard to the costs of producing it.
Depending on the facts, common deductible rental expenses can include:
- Mortgage interest
- Property taxes
- Insurance
- Property management
- Advertising
- Owner-paid utilities
- Routine maintenance
- Certain repairs
- HOA expenses
- Legal and accounting costs
Foreclosure rehabs make recordkeeping especially important because one project can contain both repairs and capital improvements.
Fixing a broken component may qualify as a current expense in the right circumstances, while replacing a roof or substantially improving a system may need to be capitalized.
Do not hand your tax professional one line that says “rehab — $47,500.” Break invoices down by the work performed and keep the receipts.
Cost Segregation Can Move Some Deductions Forward
A standard residential rental building is depreciated over 27.5 years, but every component of the property does not necessarily share that life.
Cost segregation identifies qualifying items that may fall into shorter recovery periods, such as 5, 7, or 15 years. Depending on the property, that can include certain appliances, finishes, electrical components, fencing, landscaping, and site improvements.
Current law also restored permanent 100% first-year bonus depreciation for qualifying property acquired after January 19, 2025. The IRS bonus-depreciation guidance explains the current rule. Shorter-life components identified through cost segregation may qualify, although the residential rental building itself generally does not receive that 100% write-off.
Still, bigger deductions are not automatically better. Passive-loss limits or a short holding period can reduce the immediate benefit.
Before paying for a study, compare the likely tax savings with the study cost, your expected hold period, and your ability to use the deductions.
Rental Losses May Offset Other Income in Some Cases
Depreciation and operating expenses can push a rental into a tax loss even when the property has positive cash flow.
Whether that loss helps you today depends on the passive-activity rules.
The IRS generally treats rental real estate as passive. However, if you actively participate, you may be able to deduct up to $25,000 of rental real estate losses against nonpassive income. That allowance begins phasing out when modified adjusted gross income exceeds $100,000 and is generally gone at $150,000.
A different result can apply if you qualify as a real estate professional and materially participate in the rental activity.
Suspended passive losses may carry forward rather than disappear, becoming useful against later passive income or after a qualifying taxable disposition.
The phrase “real estate creates paper losses” skips an important step: a deduction only helps when the tax rules let you use it.
A 1031 Exchange Can Work for a Foreclosure Rental
A foreclosure bought below market, renovated, and held as a rental can appreciate substantially.
When you eventually sell, a Section 1031 exchange may let you defer recognition of gain by moving into other qualifying real property held for investment or business use.
The IRS guidance on sales and exchanges draws an important line: real property held for investment or productive use in a trade or business may qualify, while property held primarily for sale does not.
For foreclosure investors, that rule is critical.
You might buy a distressed single-family house, rehab it, rent it for several years, and later exchange into a duplex or larger rental. A property acquired mainly to renovate and resell, however, is a poor fit for 1031 treatment because property held primarily for sale is excluded.
The gain is deferred, not erased, and strict identification and closing deadlines apply.
Among the tax benefits of foreclosure investing, 1031 treatment can be powerful for long-term portfolio builders. It is not a way to roll one ordinary flip into the next without tax.
Holding a Flip for 13 Months Does Not Fix the Tax Treatment
Another common shortcut is to assume that keeping a foreclosure longer than one year automatically turns the profit into long-term capital gain.
The holding period is only part of the story.
IRS guidance treats property held mainly for sale to customers in the ordinary course of a trade or business as a noncapital asset. If you regularly buy foreclosures, renovate them, and sell the finished houses, the profit may be ordinary business income even when one project runs longer than twelve months.
By contrast, real estate genuinely held for investment or used in a rental business can receive different treatment when sold.
Intent, actual use, frequency of sales, and the surrounding facts all matter. Simply waiting until day 366 is not a sound tax plan.
For a flipper, underwrite the project using the tax treatment that fits a resale business, then have your CPA confirm how the rules apply to you.
Refinancing Can Let You Reach Equity Without Selling
Taxes can also influence the decision to keep a successful foreclosure instead of selling it.
Suppose you buy a distressed house for $180,000, spend $40,000 on the rehab, and stabilize it as a rental worth $300,000.
A later refinance may let you pull out part of the equity while keeping the property.
Loan proceeds generally are not income because the money has to be repaid. That can make a BRRRR-style strategy attractive: you may recover part of your invested capital without triggering the same taxable sale that would occur if you sold the property.
One follow-up issue deserves attention: interest deductibility on refinanced debt can depend on how the proceeds are used. Keep a clean record of where the money goes.
QBI May Add Another Benefit for Some Investors
The Qualified Business Income deduction under Section 199A can provide another benefit for eligible pass-through business income.
Rental real estate does not automatically qualify. Depending on the facts, a rental may qualify as a trade or business or under the rental real estate safe harbor. A flipping business may also generate income relevant to QBI.
Because limits can change with taxable income, wages, property, and other factors, do not assume a flat 20% deduction on every dollar of real estate profit.
Long-Term Holds Can Create an Estate-Planning Benefit
Foreclosure investing does not always end with a sale.
A property bought at a discount and held for decades may eventually become part of an estate plan. Under current federal rules, inherited property generally receives a basis tied to fair market value at the owner’s date of death, subject to exceptions.
For example, a rental bought years earlier for $200,000 might be worth $600,000 when the owner dies. The heir’s basis may generally be reset to the applicable estate value rather than carrying over the original $200,000 basis.
State rules, ownership structure, and estate-specific facts can change the result, but the basis adjustment can materially reduce taxable appreciation for heirs.
The Same Foreclosure Can Produce Three Different Tax Stories
One example pulls the pieces together.
Assume you acquire a foreclosure for $180,000 and spend $40,000 on the rehab.
Sell it after renovation
If you bought the house mainly to renovate and resell in your flipping business, the profit may be ordinary business income. Depreciation and a 1031 exchange generally are not the core tax tools for that strategy.
Keep it as a rental
Place the house in service, and you may begin depreciating the qualifying basis while deducting allowable rental expenses. Cost segregation could accelerate depreciation on eligible components, while passive-loss rules determine when some losses can be used.
Later, a qualifying 1031 exchange may allow you to move into another investment property while deferring gain.
Refinance and hold
Instead of selling, you may refinance after the rehab and access some created equity without a taxable sale. Rental deductions continue while you own the property, and long-term ownership can eventually bring estate-planning rules into the picture.
The acquisition is the same. So is the rehab. The tax path is very different.
That is the practical value of understanding the tax benefits of foreclosure investing before you commit to an exit.
Do the Property Math Before the Tax Math
Tax planning can improve a good foreclosure investment. It cannot repair a bad one.
A deduction is worth only a fraction of the expense that created it. Spending $20,000 solely to get a deduction does not put $20,000 back in your pocket.
The same caution applies to cost segregation, 1031 exchanges, and depreciation. None of them will fix an inflated ARV, weak rental demand, excessive financing costs, or a rehab budget with no contingency.
Underwrite the property first:
- Purchase price
- Repair budget
- ARV
- Realistic rent
- Financing
- Holding costs
- Insurance and taxes
- Vacancy
- Selling expenses
- Expected cash flow or flip profit
After those numbers work, add the tax layer.
That order also makes our free real estate investor calculators more useful. Model the property economics first, then have your tax adviser evaluate how the planned exit changes the after-tax result.
Choose the Exit Before the Tax Break Chooses It for You
Foreclosure investors have a real tax advantage when they understand how property use changes the rules.
A rental can create depreciation and operating deductions. Cost segregation may pull some deductions forward, while passive-loss rules determine when you can use them. Investment property may qualify for a 1031 exchange, and refinancing can provide access to equity without a sale.
A flip follows a different path.
Do not keep a poor rental just because depreciation looks attractive, and do not stretch a flip past one year because you expect the calendar alone to produce capital-gain treatment.
The best tax benefits of foreclosure investing come after the underlying deal already works.
Decide how you expect to make money on the property, keep records that support that plan, and bring your CPA or tax attorney into the deal before a major sale, exchange, cost-segregation study, or change in strategy.
You might also like:
 Best Markets for Foreclosure Investing in 2026
 Treasury Yields and Distressed Housing Deals
 Broker Price Opinions in Foreclosure Deals Explained
 Foreclosure Investing: How to Buy, Analyze, and Profit From Foreclosed Homes
 Riverside–San Bernardino Foreclosure Market 2026
 Before You Buy a Tear-Down Foreclosure, Prove the Deal