How to Find Auction Foreclosure Property Before Bidding
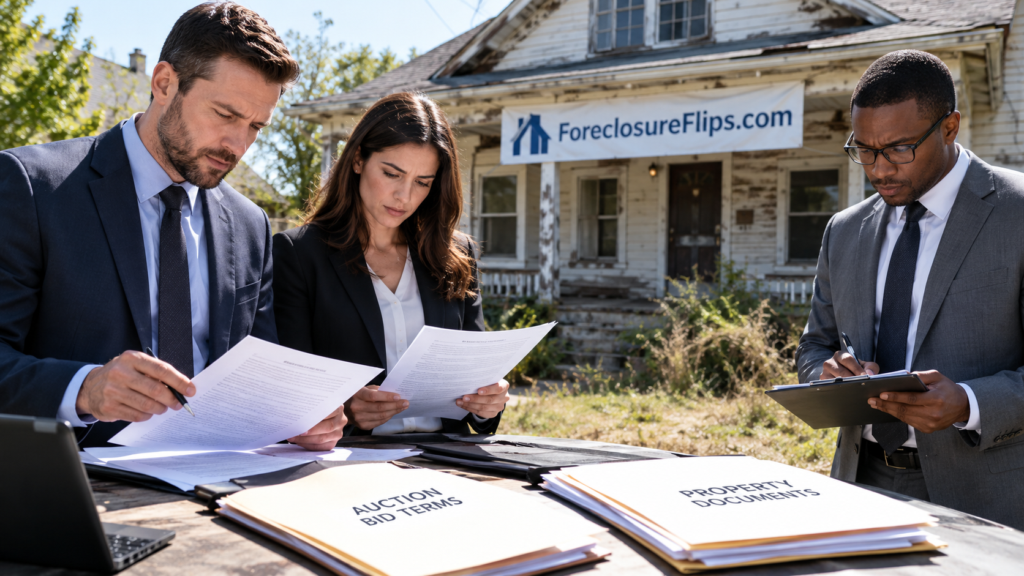
Auction foreclosure property deals compress decisions that conventional purchases spread across weeks. A published sale date, bid increments, and deposit rules may create access to properties before a conventional listing reaches the market.
The same compressed timetable puts title, condition, funding, and possession questions at the front of the analysis. Each auction type has its own terms, and a winning bid can create commitments that are difficult to unwind.
This guide shows where auction listings appear and how sale terms affect the maximum bid. It also identifies the details that belong in a property file before the sale date. The final section covers the work that begins after a high bid is accepted.
Get Foreclosure Investing Insights Twice a Week
Subscribe to the Foreclosure Flips newsletter for practical ideas on finding deals, analyzing opportunities, and understanding foreclosure-related investing strategies. We send concise updates twice a week so you can stay informed without adding more noise to your inbox.
Auction type determines the terms of sale
An auction is a sale channel with several different legal and operational paths. A court-directed foreclosure auction, trustee sale, tax-deed sale, government disposition, and lender-sponsored online auction may all involve competitive bidding. They differ in who conducts the sale, how title transfers, what liens or claims may survive, whether a redemption period applies, and how quickly funds are due.
Court-directed foreclosure sales
Court-directed sales follow the final judgment, local statute, and the rules of the clerk, sheriff, or court-appointed official handling the sale. The court file, notice of sale, legal description, and sale calendar form the first layer of research. Published addresses may be incomplete or absent, so the legal description and parcel number often connect the case to assessor, recorder, tax, and mapping records.
Pasco County’s sale and bidding information illustrates the scale of local variation. Its clerk conducts foreclosure sales under Florida law, requires registration through its designated auction site, and describes property as sold as-is. The same page warns that a clerk-issued title is not warranted free of potential claims and places property, lien, encumbrance, use, and condition research with the bidder.
Tax-deed and government auctions
Tax-default and tax-deed auctions arise from unpaid property taxes rather than a mortgage foreclosure judgment. The deed type, redemption rules, title-insurance availability, and notice requirements can differ sharply from a judicial foreclosure sale. Government auctions may involve seized, forfeited, or surplus real property and use their own sale contracts and registration process.
The sale label alone does not establish the risk profile. A tax deed may carry a different title path from a foreclosure certificate, while a government deed may offer a different level of warranty from a county-issued instrument. The terms for the individual sale set the relevant dates, costs, and transfer conditions.
Where auction properties appear before the sale date
A useful auction search starts with the source that controls the sale. County clerk, sheriff, public trustee, tax collector, or court websites usually publish a calendar, notice, case number, legal description, bidding portal, or terms of sale. Local legal notices and auction-platform schedules can add sale dates and property details, though each detail still benefits from confirmation against the official record.
A focused market file helps turn a sale notice into a property lead. The file can bring together the street address, parcel number, case number, sale date, opening bid, legal description, assessed value, tax status, zoning, recent sales, likely occupancy, and links to source documents. That record creates a place to compare several auctions without mixing the rules or costs from one property with another.
An auction calendar also gives the investor time to observe how a local sale works. Watching completed auctions, withdrawn properties, opening bids, bid increments, and any move from the sale calendar into lender-owned inventory builds a clearer picture of the market. Some assets return to the lender when third-party bidding falls short, which can create a separate REO opportunity after the auction process ends.
For research in a defined market, auction listings on Foreclosure.com add scheduled property leads and advertised sale details to the local watchlist. Those listings are a starting layer; the controlling auction notice, public records, and property-specific terms establish the information used for a bid decision.
Registration, deposits, and payment deadlines
The funding timetable often begins before bidding opens. An online platform may require account registration, identity verification, vesting information, a bidder deposit, or proof that funds have cleared before participation. Live auctions may require a certified check, cashier’s check, or another approved form of deposit at registration. A bidder who learns the accepted payment method after the deadline may lose the ability to participate in that sale.
The payment window after a successful bid can be even tighter. In Lake County, Florida, the clerk’s foreclosure-sale FAQ requires an immediate five-percent deposit from the successful bidder and the balance plus applicable costs by 4:00 PM that day unless the final judgment states otherwise. That timing is an example, rather than a national rule, but it shows why auction capital needs to match the exact sale terms.
The bid amount rarely represents the complete cash requirement. Registry charges, transfer taxes, recording fees, buyer premiums, platform fees, documentary stamps, title work, insurance, occupancy costs, repairs, and carry expenses can all affect the acquisition basis. A complete auction worksheet separates the immediate funds required to win from the cash needed to own, secure, repair, and exit the property.
Funding sources also have practical limits at auction. Conventional mortgage underwriting often fails to match a same-day payment deadline, while private capital, a line of credit, and cash each have their own draw and documentation timing. The available capital needs to align with the sale calendar, approved payment method, and vesting entity named in the registration. An account with sufficient funds but no way to deliver them in the required form by the deadline does not support a live bid.
Exit value and total cost set the maximum bid
Exit analysis begins with the likely exit rather than the opening bid. A resale plan starts with recent closed comparables, buyer demand, expected days on market, and the level of repair supported by the neighborhood. Rental assumptions use achievable rent, taxes, insurance, maintenance, financing, vacancy, and local property-management costs. The result is a ceiling that reflects the property’s future value and the investor’s full cost, rather than the excitement of a live bidding screen.
Condition drives much of that calculation. Roof failure, water intrusion, damaged mechanical systems, structural movement, fire damage, deferred maintenance, code violations, and vandalism can change the budget quickly. Where lawful access is unavailable before the auction, the model carries a larger condition allowance and a lower bid ceiling because repair certainty is limited.
The hold period needs room for events that occur after the sale. A court confirmation, deed recording, redemption period, title work, possession process, utility restoration, permits, or contractor scheduling can delay the renovation or resale. Carry costs continue through that time, even if the auction purchase price looked favorable on sale day.
For projects that may need repairs before a sale or rental exit, Rehab Valuator brings acquisition, repair, financing, holding costs, and exit assumptions into one project model. A downside version with higher repairs, a slower resale, or lower rent shows how much margin remains after the auction is over.
Title, occupancy, and inspection limits
Auction research has to account for what the buyer receives and when the buyer receives it. A sale certificate, sheriff’s deed, tax deed, trustee’s deed, or government deed may each have different effects. Recorded mortgages, tax obligations, municipal charges, judgments, easements, homeowners’ association claims, and bankruptcy filings require property-specific analysis rather than assumptions based on the sale label.
A title report or attorney review explains the chain of title, outstanding recorded interests, and the form of deed contemplated by the terms of sale. Lake County’s FAQ states that its clerk does not guarantee clear title and identifies title companies and attorneys as places to obtain title research. That reflects a practical auction reality: the auction administrator runs the sale, while title professionals assess the transfer risk.
Property access and condition evidence
Auction property is frequently offered as-is with limited or no interior access. Exterior observations from public areas, satellite images, prior listing photographs, permit records, code-enforcement information, and utility history may reveal useful clues. Scheduled open houses or inspections, when provided, are the only lawful opportunity to inspect the asset more closely.
The U.S. Treasury’s real-property auction FAQ states that property is sold as-is and describes scheduled inspections as the opportunity for bidders to examine it. The same guidance says unauthorized access is prohibited. A repair budget built from partial evidence needs enough contingency to account for the unknown interior condition.
Possession and existing occupants
Possession has its own timeline and expense. A property can remain occupied after a sale, and the new owner may need to follow state and local procedures before gaining possession. Existing tenants, former owners, personal property, leases, and utility status all influence the first weeks after title transfers.
The anticipated possession date belongs in the underwriting. Insurance, site security, legal costs, rehabilitation start date, rental income, and resale timing depend on when the investor can lawfully take control of the property. A project model that begins repairs on the sale date may understate both the cost and the calendar time involved.
The terms that change the purchase price
Auction terms convert a headline bid into a purchase obligation. The document package may address the deposit, approved payment method, final payment deadline, buyer premium, sale fee, transfer tax, deed type, recording process, risk of loss, closing requirements, bid increments, minimum bid, reserve, title language, and the consequences of default. Every item affects either cash required, time required, or risk carried by the winning bidder.
Government auction terms provide a useful example of that relationship. The Treasury explains that a successful auction bid establishes a legally binding contract, with the specific terms of sale controlling the deposit, payment, deed, and closing process. Its FAQ also notes that a closing is usually required within 45 calendar days or sooner, while the property-specific terms set the actual arrangement.
A deadline carries a cost beyond the calendar. Missing a required deposit or final payment can lead to a default, lost deposit, fees, or a restriction from future sales, depending on the auction rules. Bid increments also change the final ceiling. An online platform may extend closing time when bids arrive near the end, while an in-person auction may move faster than expected. The maximum amount incorporates the next permitted increment instead of a number that cannot be entered after another participant bids. Those terms belong in the property file before any number is entered as a planned bid.
After the high bid: payment, possession, and project start
Work after a winning bid begins with funds and paperwork. The auction administrator may require immediate payment, final funds by a stated cutoff, vesting documentation, deed instructions, tax forms, and a receipt or certificate of sale. A court or government seller may also have confirmation, recording, or closing steps before the purchaser receives the final deed.
Once the transfer permits possession, the investment shifts from auction analysis to property operations. Insurance, site security, utilities, lawful possession, full inspection, contractor scope, permit research, and repair scheduling establish the practical starting point for the project. The condition findings at that stage can confirm the earlier model or require a reassessment of the exit.
A well-prepared auction acquisition file makes that transition more orderly. It contains the sale terms, proof of funding, title materials, property research, bid ceiling, contact details, payment instructions, insurance plan, and first-week property checklist. That preparation keeps the purchase grounded in the same numbers and records that supported the bid. Auction foreclosure property deals begin with a documented bid ceiling and remain viable when the deed, condition, and possession date differ from initial assumptions.
You might also like:
 Buying REO Properties: Essential Guide for Investors
 REO Property Negotiation Tips for Real Estate Investors
 Are $100 Down HUD Homes Worth It for Investors?
 Before You Buy a Tear-Down Foreclosure, Prove the Deal
 Foreclosure Environmental Due Diligence Before You Buy
 Why Tax Benefits of Foreclosure Investing Depend on Your Exit