How Rising Household Debt Creates Foreclosure Opportunities
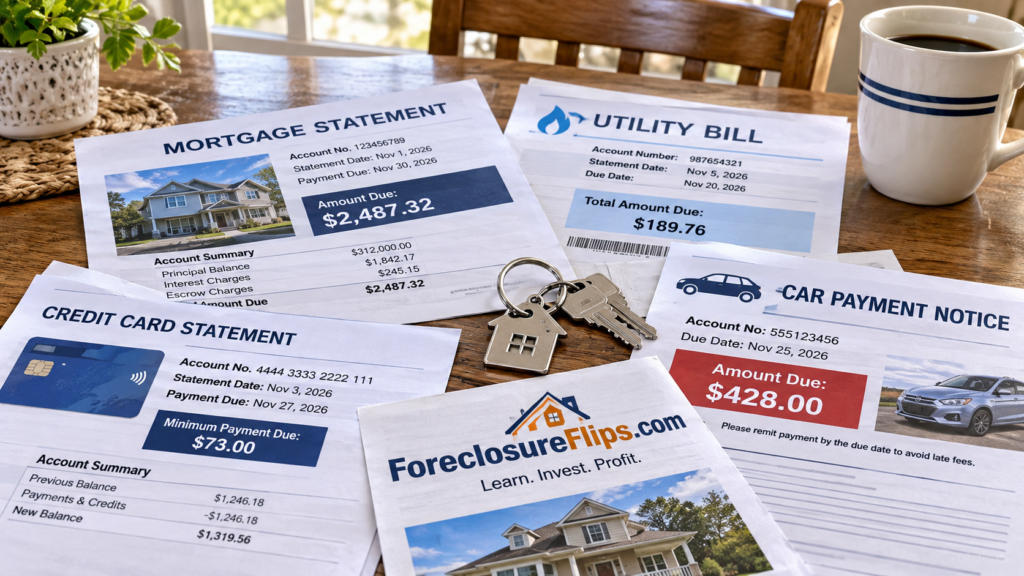
A homeowner can keep making the mortgage payment while the rest of the household budget deteriorates. Credit-card minimums rise, an auto loan absorbs more income, a HELOC balance grows, and savings gradually disappear.
That is where household debt foreclosure opportunities can begin: before the mortgage itself becomes delinquent.
For you, the useful signal is not a record national debt balance. It is the point when consumer obligations reduce a homeowner’s financial flexibility enough to affect the property.
Build Your Investing Knowledge One Email at a Time
Foreclosure investing rewards preparation. Join our 2X week newsletter for straightforward guidance on pre-foreclosures, short sales, BRRRR, flipping, and other strategies investors use to evaluate distressed property opportunities.
Start With the Bills Competing With the Mortgage
Consider a homeowner with a $1,650 monthly mortgage payment.
The mortgage remains current, but the household also pays $720 on an auto loan, $640 in credit-card minimums, and $410 on a HELOC.
Those four payments consume $3,420 per month before food, utilities, insurance, transportation, and other living expenses.
Then overtime disappears.
The owner may protect the mortgage first because losing the house carries the greatest consequence. Credit-card balances can climb and emergency savings can fall for months before the first mortgage payment is missed.
The New York Fed’s Household Debt and Credit data tracks mortgages, credit cards, auto loans, student loans, HELOCs, and delinquency transitions. The direction of repayment performance matters more to a foreclosure investor than the headline balance alone.
A Record Debt Balance Does Not Equal a Foreclosure Wave
National household debt tends to grow over time as home prices, mortgage balances, incomes, population, and consumer borrowing change.
Higher balances therefore do not automatically indicate widespread financial distress.
The more useful question is whether required debt payments are becoming harder to carry.
The Federal Reserve’s household debt-service ratio measures mortgage and consumer debt payments relative to disposable personal income. Combined with delinquency trends, it gives you more information about household pressure than total debt alone.
Watch Consumer Delinquencies Before Mortgage Distress Appears
Credit cards and auto loans can provide an early indication that household cash flow is weakening and bankruptcy may be just around the corner.
A homeowner who falls behind on an unsecured account may still keep the mortgage current. Another borrower may recover after a temporary income loss. Someone with substantial equity may decide to sell long before foreclosure becomes likely.
That means rising consumer delinquency is a reason to increase research, not a reason to assume distressed inventory is imminent.
The signal becomes more relevant when mortgage performance also starts weakening.
The OCC’s Mortgage Metrics reporting tracks current mortgages, serious delinquency, foreclosure starts, and loan modifications across a large servicing portfolio.
When consumer credit problems and mortgage delinquency begin moving in the same direction, the connection to housing becomes stronger.
Follow One Household From Debt Stress to a Possible Sale
Return to the homeowner with the $1,650 mortgage.
The first problem is lost overtime. Credit cards absorb ordinary expenses for several months.
Then the HVAC system fails.
An $8,000 replacement is difficult to fund because the household has already used most of its available revolving credit. The owner draws additional money from the HELOC and delays other bills.
Nothing guarantees foreclosure from this point.
The household may recover its income. The borrower may obtain loss mitigation. A family member could provide help. The owner may list the house conventionally.
Another possibility is a direct sale before the mortgage problem becomes severe.
That is the point where household debt foreclosure opportunities become property-specific rather than economic theory.
Use a 90-Day Lead Timeline Instead of Waiting for the Auction
When you identify a potentially distressed property, track what changes rather than treating the lead as either “good” or “bad.”
Day 1 — Establish the Property Baseline
Record:
Owner: ____________________
Estimated as-is value: $____________________
Known first mortgage: $____________________
Known junior liens or HELOC: $____________________
Estimated repairs: $____________________
Foreclosure filing located: Yes / No
Property occupied: Yes / No / Unknown
At this stage, you are building the file. Do not assume the owner wants to sell simply because financial pressure may exist.
Day 30 — Check Whether the Property Situation Changed
Update:
New default filing: ____________________
Tax delinquency: ____________________
Listing status: ____________________
Price reduction: ____________________
Code or property issue: ____________________
Owner contact or response: ____________________
The key question is whether household pressure has begun producing a property-level event.
Day 60 — Recalculate Equity and Timing
Recheck the estimated mortgage payoff, HELOC or junior debt, taxes, judgments, repair exposure, and current property value.
Write down:
Estimated usable equity: $____________________
Known foreclosure deadline: ____________________
Estimated seller proceeds at your price: $____________________
Your maximum acquisition price: $____________________
A lead that looked attractive 60 days earlier can become unworkable if another lien, additional interest, or property deterioration reduces the available margin.
Day 90 — Decide Whether the Lead Is Actionable
Classify the property as:
Monitor — financial strain exists, but no immediate property decision is visible.
Direct-sale opportunity — the owner has usable equity and a sale could resolve the property problem.
Short-sale candidate — debt may exceed the proceeds available from a conventional investor purchase.
Foreclosure-track lead — the property has moved deeper into the formal default process.
Remove from pipeline — equity, title, price, or seller circumstances do not support the acquisition.
This timeline gives you a repeatable way to watch financial stress become—or fail to become—a real property opportunity.
Calculate Usable Equity Before You Make an Offer
Assume the house is worth $325,000 as-is.
The first mortgage payoff is $214,000. A HELOC adds $38,000. Delinquent taxes total $4,500, and estimated seller-side closing costs add another $10,000.
That leaves roughly $58,500 before other liens, judgments, negotiated seller proceeds, or transaction-specific expenses.
The owner is financially stressed, but the property still has equity.
For household debt foreclosure opportunities, that equity calculation is central. A motivated owner without sufficient equity may not be able to complete the transaction you are proposing.
Verify current payoffs, liens, taxes, as-is value, and closing costs before treating estimated appreciation as available seller equity.
Check HELOCs Before You Rely on Apparent Appreciation
Home-equity borrowing can affect both the owner’s monthly cash flow and your acquisition economics.
A property may appear to have $100,000 of equity when you compare market value with the first mortgage. A $45,000 HELOC can cut that figure nearly in half.
Other claims can reduce it further.
Do not infer financial trouble simply because an owner has a HELOC. Once a property enters serious due diligence, however, confirm the outstanding balance and lien position.
A HELOC belongs in the title and payoff analysis, not just the household-budget story.
Look for Sales Before the Foreclosure Auction
Many distressed owners with equity will never reach a foreclosure auction.
Some respond to the first missed payments. Others act after a notice of default, tax problem, failed listing, or contact from their servicer.
That creates acquisition opportunities earlier in the process.
Pre-foreclosure research can include public default filings where available, tax delinquency, vacant-property information, failed listings, probate, code issues, and direct seller inquiries.
Each signal requires verification. None proves that the owner wants to sell.
Do Not Assume Financial Stress Means a Deep Discount
A homeowner can need a quick sale while still owning valuable equity.
The owner in the example may know that the house is worth roughly $325,000. A cash-flow problem does not erase that value.
Your offer has to compete with the owner’s alternatives: list with an agent, negotiate with the lender, borrow elsewhere, sell to another investor, or resolve the temporary income problem.
Speed and certainty can have value, but the purchase still has to work for both parties.
Check Whether Household Debt Is Also Weakening Your Exit
Consumer stress can affect buyers as well as distressed sellers.
A household carrying larger auto, credit-card, or student-loan payments may qualify for a smaller mortgage. Weak employment can further reduce purchasing power.
That creates a possible two-sided effect: more motivated sellers and fewer qualified retail buyers.
For a flip, test a lower resale value and longer marketing period. If you plan to hold the property, use conservative rent and vacancy assumptions. A refinance model should account for the possibility of a lower appraisal or tighter leverage.
Do not underwrite the acquisition using distress while underwriting the exit as though the broader market remains untouched.
Compare National Debt Trends With Local Foreclosure Activity
Household debt is national. Foreclosure investing is local.
A metro with strong employment, high homeowner equity, and limited mortgage delinquency may produce few distressed opportunities even when national consumer balances rise.
Another market can face weaker employers, rising taxes, high insurance costs, and increasing default activity at the same time.
Track your target counties separately.
Watch notice-of-default filings where applicable, scheduled sales, distressed listings, REO inventory, price reductions, days on market, employment, and investor competition.
That local file tells you whether national financial pressure is reaching properties you can actually buy.
Increase Lead Research Before You Increase Purchase Volume
When household financial stress increases, expand the number of properties you investigate before expanding the number you purchase.
Review more default filings. Verify more equity positions. Follow failed listings. Recheck payoffs on older leads. Track owners whose timelines are changing.
Then let property-level underwriting decide which leads advance.
The strongest household debt foreclosure opportunities occur when three things intersect: the owner faces a genuine property decision, enough equity exists to complete a sale, and your acquisition price still supports the required return.
Household debt data can tell you when to look harder. The 90-day property file tells you when there is actually something worth buying.
You might also like:
 Foreclosure Investing for Beginners: Complete Step-by-Step Guide
 How to Find Foreclosure Properties Before They Hit the Market
 Pre-Foreclosure Leads for Investors: Where to Find the Best Deals
 Finding Your First Foreclosure Deal: Tips for New Investors
 How to Choose Comparable Sales for Foreclosure Deals
 Non-Judicial Foreclosure Timelines and Investor Risk