How to Choose Comparable Sales for Foreclosure Deals
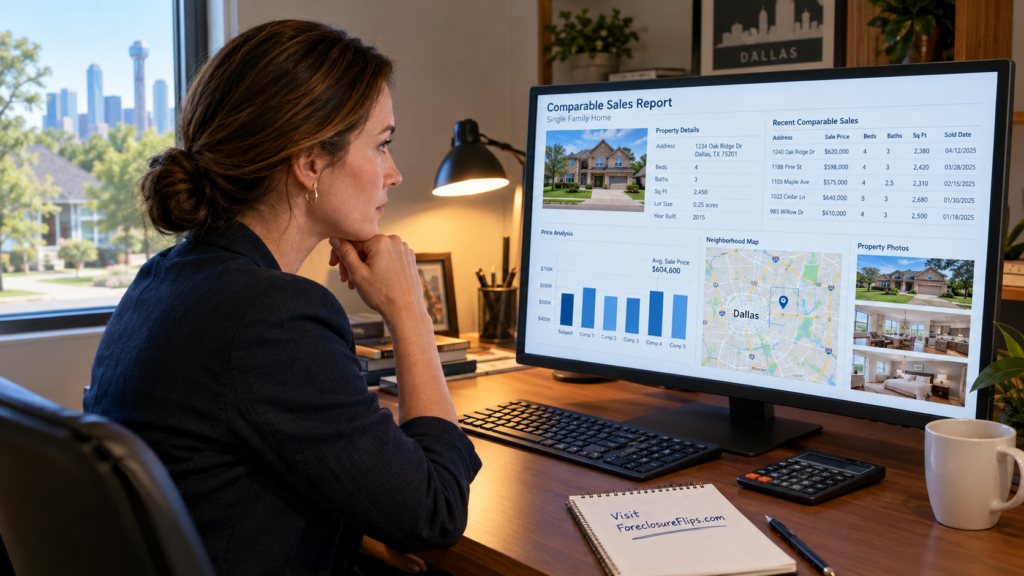
A foreclosure can sit near eight recent sales and still have only two or three useful comps. One nearby house may be fully renovated, another may sit across a school boundary, and a third may have sold at auction under terms that ordinary buyers never faced.
Choosing foreclosure comparable sales means identifying properties that competed for the same buyers under reasonably similar conditions—not collecting the closest or highest sale prices.
The goal is to build one comp set for the property you are buying now and, when the strategy calls for it, a separate set for the renovated property you expect to sell later.
Build Your Investing Knowledge One Email at a Time
Foreclosure investing rewards preparation. Join our 2X week newsletter for straightforward guidance on pre-foreclosures, short sales, BRRRR, flipping, and other strategies investors use to evaluate distressed property opportunities.
Build a Candidate Pool Before You Pick the Final Comps
Assume you are evaluating a 1,650-square-foot foreclosure that needs a kitchen, flooring, paint, and roof work. A broad search produces seven closed sales:
| Candidate | Sale price | Initial issue |
|---|---|---|
| A | $238,000 | Dated condition, same subdivision |
| B | $312,000 | Fully renovated, same subdivision |
| C | $246,000 | Estate sale, similar condition |
| D | $325,000 | Renovated, across school boundary |
| E | $218,000 | Foreclosure auction sale |
| F | $251,000 | Similar house, nine months old |
| G | $279,000 | 450 more square feet and larger garage |
Do not average the seven prices. Use the larger pool to identify which properties truly compete with the subject.
The Appraisal Institute’s comparable-selection guidance says the best comparables are the sales most similar in location, size, condition, and other features buyers and sellers recognize as affecting price.
Record Why Each Sale Belongs in the Pool
For every candidate, note the sale date, market area, property type, size, lot, bed and bath count, garage, condition, sale type, concessions, and verification source.
That record forces you to justify the comp before its price influences the valuation.
Remove Sales From the Wrong Buyer Market
A comp should resemble a property a buyer might reasonably have chosen instead of the subject.
Candidate G is nearby, but its additional 450 square feet and larger garage can place it in a different price tier. Although Candidate D is physically similar, a school boundary separates it from the foreclosure.
Match the House Before You Compare the Price
Start with property type, size, design, utility, room count, lot characteristics, parking, and major amenities.
Perfect matches rarely exist. The better comp usually requires fewer important assumptions, not a price closest to the value you hope to prove.
Treat Neighborhood Boundaries as Buyer Boundaries
A one-mile radius does not define a market.
School assignments, flood zones, gated entrances, waterfront access, HOA boundaries, major roads, municipal lines, traffic exposure, and housing quality can separate nearby properties into different buyer pools.
Freddie Mac’s current market-area guidance specifically cautions that distance parameters such as one mile are poor proxies for a neighborhood.
If buyers consistently pay more across the school boundary, Candidate D should not receive equal weight simply because it appears inside the search radius.
Separate Current-Condition Sales From Renovated Sales
The foreclosure creates two different valuation questions.
What would buyers pay for the property in its present condition? A second question asks what the completed property might sell for after the proposed renovation.
Trying to answer both with the same three sales is where comp analysis starts to drift.
Use Dated and Repair-Heavy Sales for the Acquisition
Candidates A and C deserve serious attention because their condition resembles what you are buying. Candidate F may also fit if the nine-month sale date can be reconciled with current market conditions.
These sales help estimate today’s as-is value.
A renovation budget does not turn a polished resale comp into an as-is comp. Subtracting $60,000 of planned work from a $310,000 renovated sale and calling the subject worth $250,000 assumes construction cost and market discount are identical. They often are not.
Use Renovated Sales for the Exit
Candidate B belongs in the post-rehab analysis because it resembles the finished property you intend to sell.
Match the planned finish level. A basic investor rehab should not rely on a high-end renovation with custom cabinetry, premium flooring, upgraded windows, and extensive landscaping merely because the square footage is similar.
Keeping the groups separate prevents ARV from quietly inflating the acquisition value.
Investigate the $218,000 Foreclosure Sale Before You Use It
Candidate E looks compelling because it is another foreclosure and carries the lowest price in the set.
That is not enough.
The Appraisal Institute notes that distressed sales should neither be included nor excluded solely because they involve foreclosure. Transaction circumstances, exposure, motivation, concessions, and property condition determine whether the sale provides useful market evidence.
Find Out How the Foreclosure Was Sold
A courthouse auction requiring immediate funds and offering no inspection can attract a narrower buyer pool than an REO listed through the MLS with interior access and a conventional closing period.
Check whether the sale involved:
- Open-market exposure
- Interior inspection rights
- Financing availability
- Occupancy uncertainty
- Unusual title risk
- A buyer’s premium or other auction charges
If those conditions differ sharply from the transaction you are valuing, the $218,000 price may say more about the sale process than the property’s market value.
This is why foreclosure comparable sales require transaction research as well as property research.
Keep the Nine-Month-Old Sale if It Matches Better
Candidate F closed nine months ago. That age does not automatically make it inferior to a sale from last month.
A recent property in a different location or condition may require several large adjustments. An older property that closely matches the foreclosure can provide better evidence once market movement is addressed.
Freddie Mac’s 2026 appraisal requirements call for market-condition adjustments when price changes between the comparable’s contract date and the appraisal date affect the analysis. Its guidance also requires those adjustments to be supported by market data rather than assumed.
Compare the older sale with newer closed sales, pending transactions, listings, price reductions, and days on market. If the local market moved, adjust or weight Candidate F accordingly.
Check Seller Credits Before Accepting the Recorded Price
Suppose renovated Candidate B sold for $312,000 but the seller contributed $12,000 toward closing costs and a rate buydown.
The public sale price still shows $312,000. Its transaction economics are more complicated.
Freddie Mac’s sales-concession guidance explains that the appropriate adjustment is based on the concession’s effect on the sale price, not an automatic dollar-for-dollar subtraction.
Review MLS data and agent information to verify the terms. If the incentive helped support a higher price, treating the recorded amount as an uncomplicated cash-equivalent sale can overstate the resale value.
Adjust Condition Based on Buyer Reaction
The subject needs a roof while Candidate A has a five-year-old roof. Another sale may have an extra bathroom, better view, superior lot, or newer HVAC.
Do not automatically use contractor cost as the adjustment.
A $17,000 roof estimate does not prove buyers discount the distressed property by exactly $17,000. Buyers may discount more because they face uncertainty and financing difficulty, or less because the existing roof still has remaining utility.
Use paired sales, agent evidence, and other local data to estimate how buyers price the difference. The same principle applies to kitchens, pools, garages, and lot size: adjustment should reflect market reaction, not the amount on an invoice.
Narrow the Seven Candidates to the Best Evidence
After researching the candidates, the original seven-sale pool changes:
| Candidate | Acquisition use | Resale use | Decision |
|---|---|---|---|
| A | Strong | Weak | Keep |
| B | Weak | Strong | Keep for renovated value |
| C | Strong | Weak | Keep |
| D | Weak | Moderate | Reject due to location |
| E | Uncertain | Weak | Use only if sale terms support it |
| F | Strong if time-supported | Weak | Keep |
| G | Weak | Moderate | Reject due to size and utility |
You now have three plausible as-is comps—A, C, and F—and one strong renovated comp, B, with other renovated sales still needed to support the exit.
That is a more useful foreclosure comparable sales set than an average of every nearby closing.
Give the Closest Match More Weight
Assume adjustments produce as-is indications of $239,000, $244,000, and $252,000.
The answer is not automatically $245,000 because that is the arithmetic average.
If the $244,000 comp sits in the same subdivision, has nearly identical size and condition, and required only small adjustments, it may deserve more weight than the $252,000 sale with a time adjustment and inferior location match.
The sale with the fewest material differences often tells you more than a heavily adjusted outlier. When adjusted indications remain far apart, revisit the comp pool instead of forcing the prices into a single conclusion.
Recheck the Comp Set Before Raising the Offer
Competitive bidding can make a weak comparable suddenly look persuasive.
Before increasing the offer, review the sale you are relying on. Confirm that it competes in the same buyer market, resembles the subject’s current condition, reflects a transaction you understand, and still represents current pricing.
Keep the acquisition set separate from the renovated resale set. Investigate distressed transactions instead of assuming every foreclosure is a valid comp. Use time and condition adjustments only when market evidence supports them.
A disciplined foreclosure comparable sales analysis may produce a lower value than the first radius search. That is useful information. The job of the comp set is to tell you what the property supports—not to justify the price required to win it.
You might also like:
 Treasury Yields and Distressed Housing Deals
 How to Find Foreclosure Properties Before They Hit the Market
 Pre-Foreclosure Leads for Investors: Where to Find the Best Deals
 Foreclosure Investing: How to Buy, Analyze, and Profit From Foreclosed Homes
 Riverside–San Bernardino Foreclosure Market 2026
 Foreclosure Starts vs Completed Foreclosures for Investors