How to Verify a Mortgage Payoff Amount Before Closing
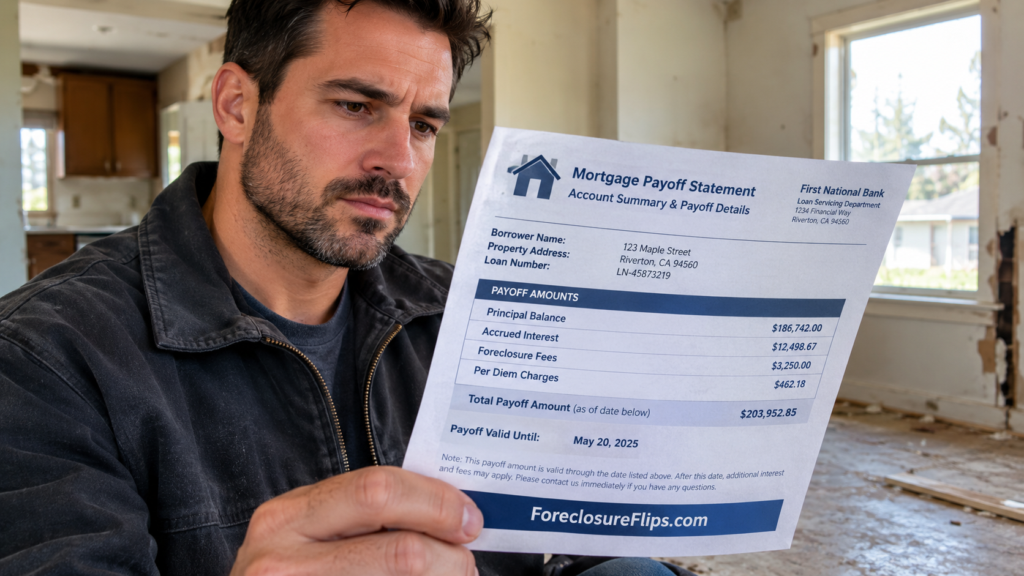
A seller may believe the mortgage balance is $142,000 while the closing agent receives a payoff for $151,800. That $9,800 difference can reduce seller proceeds, force a price change, or stop a pre-foreclosure purchase from closing.
The gap is usually explainable. Principal is only one part of the amount required to satisfy a loan on a specific date.
Before you rely on a mortgage payoff amount, verify who issued the statement, what charges it includes, how long the figures remain valid, and whether the final amount still works with the seller’s equity.
Stay Ahead of the Next Deal
Markets move quickly, and good foreclosure opportunities often require fast analysis. Subscribe to our twice-weekly newsletter for investor-focused tips, tools, and market insights designed to help you make better decisions.
Verify Who Issued the Payoff
A current online balance, monthly mortgage statement, foreclosure complaint, or verbal estimate is not the same as an authorized payoff statement.
For many consumer mortgages secured by a dwelling, the federal payoff-statement rule requires a creditor, assignee, or servicer to provide an accurate payoff balance after a written request from the borrower or someone acting on the borrower’s behalf. The rule generally requires the response within seven business days, with additional time allowed in certain circumstances such as foreclosure or bankruptcy.
Match the payoff to the correct loan
Confirm the borrower name, property address, loan number, and servicer before using the figure.
Distressed properties can have a first mortgage, second mortgage, home-equity line, judgment, or other recorded debt. A payoff for one loan says nothing about the amount required to clear another lien.
Compare the payoff statement with the title report so every mortgage or deed of trust has a corresponding plan for satisfaction.
Confirm the request was authorized
A servicer can require reasonable verification before releasing private loan information to a third party. That means a purchase contract alone may not give you access to the seller’s mortgage account.
The seller can request the statement directly or authorize the title company, closing attorney, or another representative to obtain it. Build that authorization into the transaction early enough that the payoff does not become a last-minute closing item.
Reconcile Every Charge on the Statement
Assume the seller reports a principal balance of about $143,200. The authorized payoff shows this:
| Payoff item | Amount |
|---|---|
| Unpaid principal | $143,200 |
| Accrued interest | $3,420 |
| Late charges | $780 |
| Foreclosure attorney and filing costs | $2,150 |
| Property or escrow advances | $1,600 |
| Other permitted charges | $250 |
| Total payoff good through October 20 | $151,400 |
The $8,200 difference affects seller equity immediately. Each line deserves a reason.
Start with unpaid principal
Compare the principal on the payoff with the latest mortgage statement or other recent account information supplied by the seller.
Small differences can result from payments posted after an older statement. A larger difference deserves an explanation before you finalize the settlement statement.
Trace accrued interest to the payoff date
Interest continues to accrue until the loan is satisfied under the applicable payoff terms.
Fannie Mae’s payoff-processing procedures, for example, calculate payoff interest from the unpaid principal balance using the current accrual rate and distinguish between full-month and partial-month interest calculations. The exact method depends on the loan and applicable servicing rules.
If the closing date moves, the interest figure can move with it. Do not assume that the interest shown on a payoff dated for October 20 remains accurate for an October 25 closing.
Review legal fees, late charges, and property advances
A delinquent loan can accumulate costs that are not visible in the principal balance.
Once foreclosure work begins, permitted charges may include attorney fees, filing costs, service expenses, publication costs, property inspections, or other foreclosure-related expenses. Fannie Mae’s default-related cost guidance also allows certain legal costs and escrow or corporate advances to be included in the amount required to reinstate or pay off a loan when the note, security instrument, and applicable law permit collection.
If the servicer advanced taxes or insurance to protect the lien or property, that amount may appear in the payoff.
Compare those charges with the settlement statement so the same tax, insurance, or legal item is not counted twice.
Check the Good-Through Date Before Scheduling Funding
A payoff is calculated for a specific period. The “good through” date tells you how long the quoted total can be relied on under the statement’s terms.
Suppose the $151,400 payoff is valid through October 20 and shows daily interest of $31 after that date. A three-day delay could add about $93 before any new legal fee, tax advance, or other account activity.
Use the stated per diem only when the payoff allows it
Some payoff statements provide a per diem amount that lets the closing agent extend the figure for a limited number of days. Others require a new quote after the expiration date.
Follow the statement instead of creating your own extension.
Foreclosure files deserve extra attention because additional legal charges can accrue while the case remains active. Fannie Mae guidance specifically recognizes that servicers may shorten the validity period for foreclosure payoff or reinstatement quotes when new fees, costs, or advances can arise.
When closing is delayed, obtain an updated quote rather than assuming a simple interest extension will cover the change.
Compare the Payoff With the Foreclosure and Title Records
Court foreclosure records may state the principal balance, accrued interest, escrow shortage, and fees as of an earlier date. The title search may show additional mortgages or judgments. Neither document replaces the current payoff, but both can expose inconsistencies worth resolving.
If the foreclosure case shows a materially different balance, identify the change. Payments, credits, interest, advances, fee reversals, or post-filing legal work can explain the gap.
Recalculate Seller Proceeds With the Current Payoff
Suppose the purchase price is $180,000.
The seller believes the principal balance is $143,200 and expects roughly $36,800 of gross equity before other costs. An authorized statement puts the mortgage payoff amount at $151,400.
Gross equity falls to $28,600.
Now add a $7,000 second lien, $2,500 in delinquent taxes, and $5,000 of seller-side closing expenses. Estimated seller proceeds fall to about $14,100.
That difference can change the negotiation. An owner expecting more than $30,000 may not accept a closing statement showing less than half that amount unless the payoff and other liens were verified early.
For you, the same calculation shows whether the property has enough equity for a conventional purchase or whether some debt would need separate resolution.
Do Not Substitute a Reinstatement Quote
A reinstatement amount and a payoff solve different problems.
Reinstatement generally brings a delinquent mortgage current under the applicable loan terms. Payoff satisfies the debt in full.
An owner who wants to keep the property may focus on reinstatement. A buyer acquiring the property usually needs the existing mortgage satisfied unless the transaction uses another valid structure.
Because a reinstatement figure can be much lower, inserting it into the seller-equity calculation can make a deal appear to have equity that will not exist at closing.
Use the document that matches the transaction you are actually completing.
Confirm the Final Amount and Delivery Instructions Before Funding
The closing agent should compare the latest payoff with the final settlement statement before funds leave escrow.
Confirm the loan number, borrower, payoff total, good-through date, permitted per diem calculation, and any required reference information. If the closing date changed, make sure the figures still cover the expected date the servicer will receive the funds.
Delivery instructions also need independent verification through the title company’s or attorney’s normal fraud-prevention process. An accurate payoff sent to fraudulent wire instructions does not satisfy the mortgage.
Once the servicer receives sufficient funds, the payoff process should lead to satisfaction and release of the lien.
Track the Mortgage Release After Closing
Payment of the debt and release of the recorded lien are separate events.
Fannie Mae’s payoff procedures require the servicer, after confirming sufficient payoff funds, to prepare the appropriate satisfaction or release documents and complete the steps needed to remove the mortgage interest from the record.
For an investor planning a quick rehab, refinance, or resale, that recorded release can become important quickly. An old mortgage that still appears open in the public record may create questions for the next title company or lender even though the prior debt was paid.
Keep the payoff statement and closing evidence in the property file, then confirm that the satisfaction or release reaches the public record.
Use the Payoff to Set the Real Equity Before Closing
A mortgage payoff amount is a dated calculation of what the servicer requires to satisfy the loan, not simply the remaining principal.
Principal, accrued interest, late charges, foreclosure legal expenses, property advances, and other permitted costs can all affect the total. The good-through date determines how long the figure remains useful, while borrower authorization controls who can obtain account information.
Verify the payoff early enough to recalculate equity before seller expectations harden around an outdated balance. Then verify it again when closing approaches.
The number that belongs in your acquisition file is the amount that will actually clear the mortgage on the day the transaction funds.
You might also like:
 Seller Financing for Distressed Property Investors
 How to Build a Distressed Property Buy Box
 Subject-To Deals in Pre-Foreclosure Investing
 When Creative Financing Does Not Fit a Foreclosure Deal
 Pre-Foreclosure Due Diligence When Tax Debt Threatens Closing
 Property Appreciation and Foreclosure Deal Analysis