Mortgage Default Stages and Investor Lead Timing
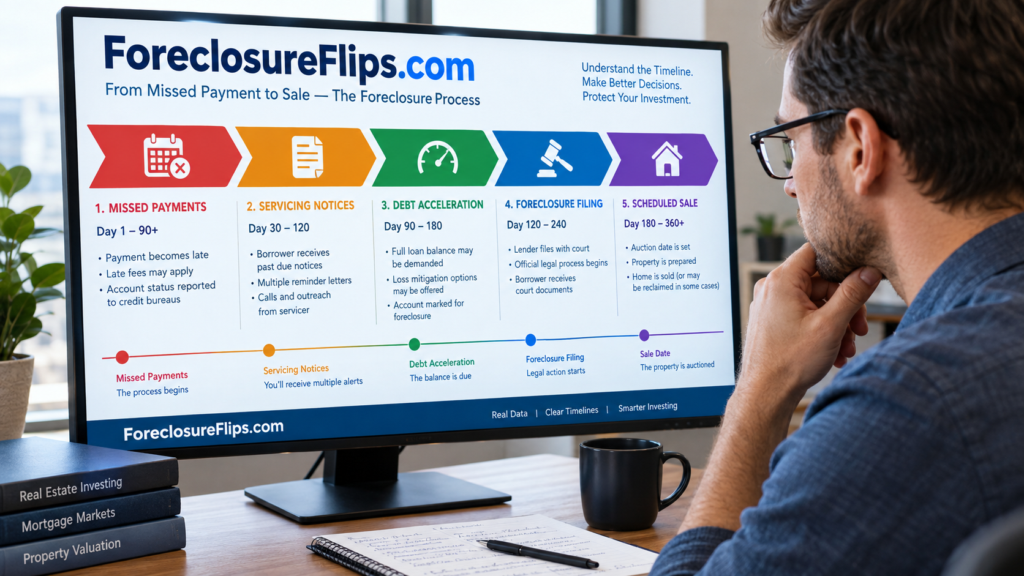
Two properties can appear on a pre-foreclosure list on the same morning and be at completely different points in the process. One owner may have just crossed the first public-filing threshold. Another property may already have a foreclosure sale scheduled in three weeks.
Treating those leads the same can waste research time and produce an unrealistic closing plan.
Understanding mortgage default stages helps you separate early distress from an active foreclosure deadline. The stage tells you what records should exist, what documents are worth requesting, and how much time may remain for a voluntary sale.
Learn the Strategies Behind Smarter Foreclosure Investing
Get practical foreclosure investing content delivered twice a week, including deal analysis tips, strategy breakdowns, useful tools, and new resources from Foreclosure Flips. Sign up to keep learning and spotting better opportunities.
The First Missed Payment Is Usually Invisible to Public Records
A mortgage becomes delinquent when a scheduled payment remains unpaid. That first missed payment normally exists inside the loan servicer’s records rather than the courthouse or county recorder.
No complaint, lis pendens, notice of default, or auction notice may exist yet. An owner can also cure an early delinquency before foreclosure starts.
What You Can Verify Before a Public Filing
If the owner contacts you during this period, the useful acquisition facts are straightforward: estimated loan balance, other liens, equity, occupancy, property condition, and whether the owner is already working with the servicer.
A single missed payment does not establish a foreclosure timeline. It tells you the loan is delinquent, not that the property will reach sale.
Days 36 and 45 Bring Servicer Contact, Not Foreclosure
For many mortgages covered by federal servicing rules, the servicer must make a good-faith effort to establish live contact by the 36th day of delinquency. A written notice describing available loss-mitigation options generally must follow by the 45th day when the rule applies.
The CFPB’s early-intervention requirements explain those 36-day and 45-day obligations.
From an investor’s perspective, this stage can still be difficult to see from public data. The owner may be discussing repayment, forbearance, modification, or another workout while the recorder and court docket remain quiet.
That makes a 30-to-60-day delinquency different from a filed pre-foreclosure. The payment problem is real, but the eventual outcome is still uncertain.
Acceleration Letters Show the Default Is Advancing
As delinquency continues, the loan documents and servicing requirements can require a breach or acceleration notice. The letter typically identifies the default, the action needed to cure it, and a deadline.
Fannie Mae’s breach and acceleration guidance requires the servicer to issue the letter no later than the 75th day of delinquency for certain conventional first-lien loans on occupied properties. Other loan types and servicing requirements can follow different rules.
What to Check in an Acceleration Letter
Look for the cure deadline, amount due, servicer name, loan number, and any language describing acceleration or foreclosure referral.
The letter can show that the default has moved beyond a routine late payment. It still does not establish that a public foreclosure case has started.
Because the notice is generally sent directly to the borrower, an investor who relies only on recorded documents may never see this stage.
The 120-Day Rule Marks the Main Federal Filing Threshold
For many residential mortgages covered by Regulation X, a servicer generally cannot make the first notice or filing required to start foreclosure until the loan is more than 120 days delinquent, subject to stated exceptions.
The CFPB’s loss-mitigation and foreclosure rule sets out that pre-foreclosure review period and explains how the first notice or filing depends on state procedure.
This is the point where mortgage default stages become much easier to identify from public records.
Judicial Foreclosure Usually Creates a Court Case
In a judicial foreclosure, the lender starts the case through the court system. Depending on state law, the first public record may be a complaint, petition, order to docket, or similar filing.
Some jurisdictions also record a lis pendens or another notice against the property.
A filing date confirms that the legal process has begun. It does not establish the eventual sale date because court schedules, loss mitigation, bankruptcy, and state procedures can extend the case.
Nonjudicial Foreclosure Uses Recorded or Published Notices
A nonjudicial foreclosure can proceed without a foreclosure judgment when state law and the security instrument permit it.
The first public event may be a recorded notice of default, published notice, trustee filing, or another document required by state law to begin the process.
Terminology varies widely. When you source leads across multiple states, the document name matters less than identifying what legal event it represents.
If you use Foreclosure.com to find public-stage leads, confirm the current status in the underlying county, court, trustee, or recorder records before underwriting the timeline.
Loss Mitigation Can Delay a Filing or Sale
A foreclosure case or recorded notice does not guarantee that the property will reach auction on the first date you see.
Borrowers may submit a loss-mitigation application after delinquency has progressed. Under Regulation X, a complete application can restrict certain foreclosure steps when the rule applies and the application arrives within specified timeframes.
For example, the CFPB rule generally prevents a covered servicer from moving for foreclosure judgment or conducting a sale after receiving a complete loss-mitigation application more than 37 days before the scheduled sale unless one of the rule’s conditions allows foreclosure to continue.
From a lead-analysis standpoint, a public filing can remain active while the practical timeline changes.
A Sale Notice Changes the Closing Calculation
Once a foreclosure sale is scheduled, the lead becomes deadline-driven.
Your research has to answer whether a voluntary transaction can realistically close before the applicable cutoff. That means verifying the current payoff, junior liens, delinquent taxes, title problems, occupancy, closing requirements, and available funding.
A property with substantial equity can still be unusable as an acquisition lead if title work and financing cannot be completed in time.
Confirm the Sale Date Again Before Closing
Scheduled sales can be postponed or cancelled. Bankruptcy filings, court orders, loss mitigation, reinstatement, or procedural issues can change the date.
Confirm the sale status again as the proposed closing approaches. An old auction date copied from a lead list is not enough to plan around.
Record the Event That Created Each Lead
Instead of labeling every property “pre-foreclosure,” record the specific event that placed it in your lead system.
| Lead event | What you can verify | What it tells you |
|---|---|---|
| Owner reports missed payments | Information supplied by the owner | The loan is delinquent, but foreclosure may not have started |
| Breach or acceleration letter | Letter supplied by the owner | The default has advanced and a cure deadline may exist |
| Complaint or lis pendens | Court or land records | A judicial foreclosure has started |
| Notice of default or equivalent | Recorder, trustee, or published record | A nonjudicial foreclosure has reached a formal notice stage |
| Notice of sale | Court, trustee, recorder, or publication | A sale date has been set, subject to change |
| Completed sale | Sale results and deed records | The owner’s voluntary pre-foreclosure sale window has ended |
This approach prevents an early delinquency lead and a sale-date lead from receiving the same research priority.
Change Your Due Diligence as Foreclosure Advances
Early-stage leads usually require more verification of the basic economics because the foreclosure deadline may still be remote or nonexistent.
Start with approximate equity, property condition, ownership, and other obvious liens. Those facts tell you whether further research is justified.
After a public filing, move payoff verification, lien priority, taxes, and title research higher on the list. The legal process is active, so the amount required to produce a workable closing becomes more important.
Once a sale is scheduled, closing time joins price as a primary constraint. Funding, title clearance, payoff delivery, occupancy, and required documents all have to fit inside the remaining window.
This is the practical value of tracking mortgage default stages: your due diligence changes with the procedural status instead of following the same checklist for every lead.
A Foreclosure Filing Does Not Mean the Owner Wants to Sell
A complaint, lis pendens, notice of default, or sale notice gives you useful timing information. None of those records proves that the owner wants to sell.
Early-stage outreach can reach an owner before the process becomes compressed, but many delinquencies resolve without a sale. Later filings provide stronger evidence that foreclosure is progressing while leaving less time to resolve liens, negotiate terms, and close.
Any outreach also has to comply with the federal, state, and local rules that apply to solicitation and foreclosure-related transactions in the market where you operate.
The strongest stage analysis combines the public event with equity, title, owner intent, and available closing time. A lead becomes actionable when those facts line up—not simply because a foreclosure-related document appeared in a database.
You might also like:
 Pre-Foreclosure Leads in an Affordability Crisis
 Lease Options for Pre-Foreclosure Properties
 How to Create a Distressed Property Lead Scorecard
 How to Track Distressed Sellers Without Chasing Bad Leads
 Skip Tracer for Real Estate: Who Can Actually Sell?
 Pre-Foreclosure vs Foreclosure: What Investors Need to Know