How to Find As-Is Foreclosure Property Deals Before You Bid
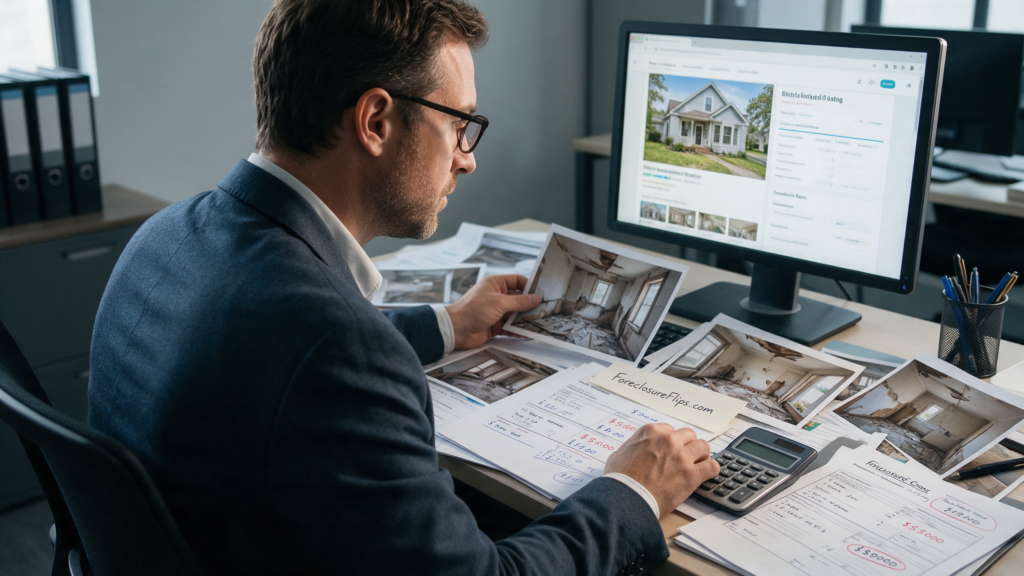
As-is foreclosure property deals can create room for a better purchase price. That discount has to cover the condition risk that stays with the buyer after closing. The listing language offers no useful repair scope on its own.
An as-is clause usually signals that the seller is unlikely to repair defects or provide a credit. It does not describe the roof, wiring, plumbing, title, insurability, or resale potential. Each of those factors still affects the price.
This guide turns an as-is listing into a condition file, repair budget, offer structure, and walk-away number. By the end, you’ll have a practical method for separating a repairable acquisition from an expensive unknown.
Get Foreclosure Investing Insights Twice a Week
Subscribe to the Foreclosure Flips newsletter for practical ideas on finding deals, analyzing opportunities, and understanding foreclosure-related investing strategies. We send concise updates twice a week so you can stay informed without adding more noise to your inbox.
An as-is clause shifts repair responsibility
An as-is sale is a contract position, not a description of physical condition. It generally says that the seller will transfer the property in its present state and has limited appetite for fixing problems found during diligence. A bank-owned home, an estate sale, a relocation disposition, or a distressed property may carry that language for different reasons.
The same words can appear on a home with dated finishes and on one with active water intrusion, an unsafe electrical panel, or a failed septic system. This contract language leaves the buyer responsible for pricing the visible and hidden work. That changes the order of analysis: condition and project cost enter the file before an offer becomes credible.
Seller disclosures, purchase-contract addenda, inspection rights, and local law remain separate questions. An as-is provision does not erase duties that apply to a transaction. For covered residential sales, the federal lead-disclosure process requires sellers to provide buyers with known lead-based-paint information and related records; the EPA’s seller disclosure guidance describes the required form. State and local rules may add further disclosures or contract requirements.
The listing is an alert, not a repair list
A short listing remark such as “needs TLC,” “cash only,” “no repairs,” or “sold as-is” gives an investor a starting question, not an estimate. Remarks may come from an agent, asset manager, executor, servicer, or automated feed. None replaces a site visit, document review, or specialist opinion.
The file begins with each condition phrase recorded exactly as written. Listing photos, prior listing history, days on market, price changes, and any seller-provided reports give those words context. A gap between the remarks and the photos often points to the next question: Why is the garage excluded from the images? Why is the basement unfinished in every photo? What brought the listing back after a pending sale?
A property file keeps observations separate from assumptions. “Staining beneath upstairs window” is an observation. “Roof replacement required” is an assumption until a qualified inspection supports it. That separation keeps the repair budget from quietly becoming a list of guesses.
Early condition research: street view and public records
Early work on an as-is deal is usually desktop research and a lawful exterior review. This first screen can reveal obvious reasons to spend more time, commission a specialist, or move on. It is not a substitute for access when the contract permits an inspection.
Exterior details often set the investigation sequence. Rooflines, gutters, downspouts, grading, retaining walls, siding, chimneys, windows, detached structures, utility meters, and visible foundation movement may reveal where the budget deserves extra attention. Neighboring properties and the block itself add context about parking, drainage, traffic, renovation activity, and market demand.
What public records add to listing photos
Assessor records, parcel maps, building permits, code-enforcement records, tax history, and recorded documents give the listing a history. An unpermitted addition, open code case, demolition order, unpaid municipal charge, or unusual easement can alter the scope and timing of a project. Title professionals and local counsel can address legal status where the acquisition calls for it.
Hazard research belongs beside the repair review. FEMA directs real-estate professionals to its flood-risk map resources for the current map and address-based searches. Flood-zone status can affect insurance pricing, loan terms, renovation planning, and eventual buyer demand, even when the home’s visible condition appears manageable.
A useful file sorts findings into four columns: physical condition, legal or title issue, financing condition, and market issue. Foundation movement belongs in the physical column. A recorded access agreement belongs in the legal column. Lender-required repairs belong in the financing column. Weak comparable sales belong in the market column. The four categories may interact, but separating them prevents one issue from obscuring another.
Inspection access determines the depth of diligence
Contract language decides when an investor can inspect, which professionals may enter, and whether findings permit a price change or contract exit. An as-is clause does not automatically remove an inspection period. In some transactions, the seller may accept an offer with an inspection contingency but decline to fund repairs. Other transactions limit access, involve a competitive sale, or expect the buyer to accept a shorter review period.
The Consumer Financial Protection Bureau’s inspection guidance distinguishes an appraisal from an inspection and explains that a satisfactory-inspection contingency may allow a buyer to cancel under the purchase contract. It also notes that major repairs can complicate financing. Those points are especially relevant when an as-is property depends on conventional, FHA, VA, or other condition-sensitive financing.
A general home inspection gives a broad condition snapshot. Its findings may point toward further review by a roofer, plumber, electrician, HVAC technician, structural engineer, septic contractor, pest specialist, mold professional, or foundation contractor. The right follow-up depends on the evidence. Moisture noted near a foundation can lead to drainage work, a plumbing leak, structural movement, or a combination of causes.
Inspection time has a cost beyond the report fee. Contractors need access to price the scope. Lenders, insurers, partners, and end buyers may each impose deadlines or standards. The offer period should allow enough time to identify the project’s major unknowns and understand whether any of them change the exit plan.
The repair scope sets the offer price
A repair budget starts with a written scope, not a round allowance. Group work by trade and by sequence: site protection and cleanup, structural or water-management work, roof and exterior envelope, mechanical systems, rough construction, finishes, permits, and final turnover. The sequencing exposes problems that a single “rehab number” can hide. Replacing flooring before resolving a plumbing leak is a poor scope sequence, even when both line items appear in the same budget.
Each line item benefits from a source and a confidence level. A contractor bid with photos and a defined scope carries more weight than a verbal estimate. Comparable-project costs may help with early screening, but they should remain marked as preliminary allowances. Unknown conditions behind walls, below slabs, or in inaccessible areas belong in a contingency reserve rather than disappearing from the model.
The property also carries costs that never appear in a contractor bid. Include lender fees, points, interest, insurance, taxes, utilities, lawn or snow service, permit fees, debris removal, closing costs, staging, sales commissions, and time. A six-month hold with a modest repair scope can produce a thinner margin than a larger project with a fast, well-supported path to market.
When the scope is defined, Rehab Valuator can organize repair, financing, holding, and exit assumptions in one project model. The model belongs at the end of the condition review, where it can test documented costs and timing instead of relying on an untested listing price.
As-is listings that warrant a closer look
As-is language appears across bank-owned listings, pre-foreclosure opportunities, probate and estate sales, auction inventory, lender dispositions, wholesale assignments, and ordinary MLS listings. A single search filter rarely captures the whole pool. Listing remarks, price reductions, failed pending sales, cash-only terms, inspection limitations, and visible deferred maintenance often reveal details that a generic “as-is” flag misses.
A focused search starts with the kind of project that fits the intended exit. Cosmetic flips have different tolerances from full-gut renovations or wholesale assignments. Price band, age, construction type, neighborhood, lot size, financing route, and target buyer determine which condition issues are acceptable. That buy box keeps attention on deals that can absorb their own repairs.
The listing file can then be refreshed as facts change. A new price, an accepted offer that returns to active status, fresh interior photos, or a revised seller disclosure may alter the underwriting. Regular review creates a record of what changed and when, which helps explain whether the opportunity improved or merely became more visible.
Foreclosure.com’s as-is property listings can add distressed and condition-driven prospects to that search process. Their value comes from widening the lead pool; a prospect moves toward an offer only after the property file, inspection access, scope, and exit numbers support it.
Offer terms follow the condition evidence
The offer price is the residual after the exit value and total project cost have been tested. Investors often use a maximum-allowable-offer calculation, but its components deserve more attention than the formula itself. The after-repair value depends on real comparable sales and the buyer segment that will purchase the finished home. Repair figures depend on scope. Holding costs depend on time, financing, and the likelihood of delay.
Contract terms carry their own price. A shorter inspection period, an earnest-money deadline, cash proof, a financing contingency, an appraisal contingency, or a request for seller access may change the seller’s response. Even a higher nominal price can be weaker when the buyer lacks a workable diligence period or cannot close under the property’s condition constraints.
An as-is offer works best when the written terms match the property’s actual stage of review. Before access, the price may reflect a broader contingency reserve. After inspection and contractor input, the same property may support a more precise number. In a competitive sale with no inspection right, the number needs enough room for the uncertainty that remains.
When the project fails the as-is test
Some red flags change the deal rather than the budget. Foundation movement without a defined cause, repeated water damage, unsafe utilities, a nonfunctioning septic system, an uninsurable roof, title defects, an occupied property with no clear possession path, or an end value unsupported by comparable sales may require a different offer structure or no offer at all.
The decision becomes clearer when each unknown has a cost range, a deadline, and an effect on the exit. A repair issue with a reliable contractor bid is different from one that requires destructive testing or regulatory approval. Financing that disappears after the appraisal differs from a lender condition with a known cure. The file should show which uncertainty remains open and how much profit is left after it is priced.
As-is foreclosure property deals reward disciplined selection, not optimism about a vague discount. A complete file connects the listing history, condition evidence, public records, inspection rights, contractor scope, financing plan, and exit value before the bid or offer goes out. That work gives the price a factual basis and keeps the project aligned with the intended flip.
You might also like:
 Private Lenders for House Flips: How to Find and Work With Them
 Real Estate Investor Mentorship for Portfolio Freedom
 Flip Property Exit Strategies: Maximizing Profit and Minimizing Risk
 Hard Money Loans for House Flipping: Pros and Cons
 Best Cities for House Flipping: Top Locations for High ROI in 2025
 A 90-Day Foreclosure Flip Timeline