A 90-Day Foreclosure Flip Timeline
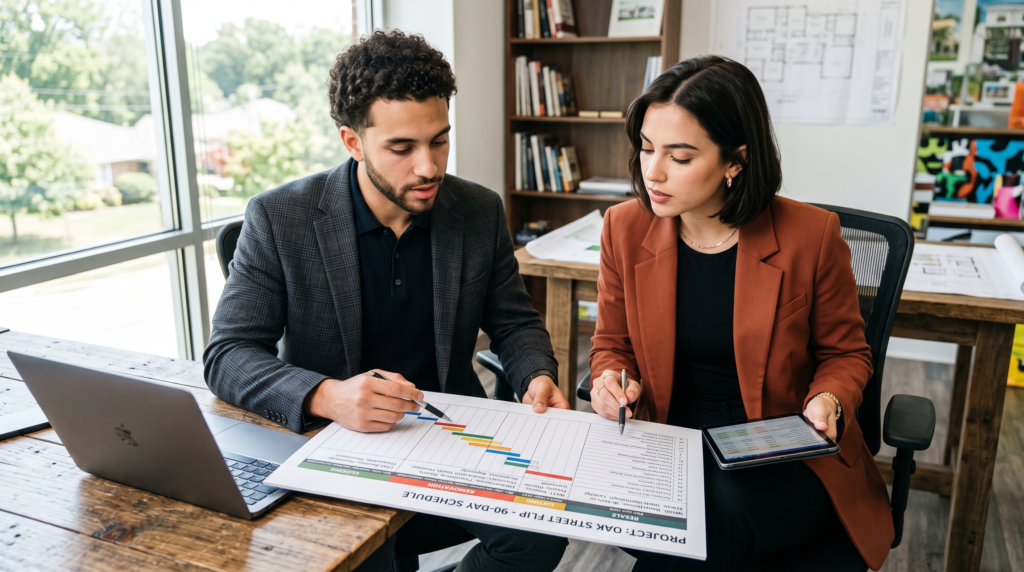
A 90-day foreclosure flip is possible when the property has a clear acquisition path, prompt possession, a defined renovation scope, and enough resale demand to secure a buyer quickly.
It is not appropriate for every foreclosure. Redemption rights, occupied-property disputes, court confirmation, title defects, structural repairs, or slow permit approvals can extend the project before construction even begins.
The purpose of a 90-day timeline is not to rush due diligence or construction. It is to eliminate preventable downtime between acquisition, cleanout, rehabilitation, listing, and resale.
For this model, Day 1 begins when your purchase contract becomes binding or your auction bid is accepted—not when contractors eventually arrive.
Get Foreclosure Investing Insights Twice a Week
Subscribe to the Foreclosure Flips newsletter for practical ideas on finding deals, analyzing opportunities, and understanding foreclosure-related investing strategies. We send concise updates twice a week so you can stay informed without adding more noise to your inbox.
Confirm That the Property Fits the Timeline
Before setting a 90-day target, decide whether enough of the schedule remains under your control.
The model is best suited to a vacant property, or one where lawful possession can be obtained immediately after closing. You should also have an insurable title path, available funding, reliable contractors, and a renovation that does not depend on extensive design work or zoning approval.
A property may be profitable without being a 90-day project. Adjust the schedule when the deal involves bankruptcy approval, probate, major environmental concerns, extensive structural work, unresolved occupancy, or a delayed deed.
Trying to force those properties into an unrealistic calendar usually produces inaccurate holding costs and rushed decisions.
The 90-Day Schedule at a Glance
| Phase | Target days | Required milestone |
|---|---|---|
| Acquisition and closing | 1–10 | Funding, title, insurance, possession, and scope confirmed |
| Security and cleanout | 11–18 | Property secured, emptied, tested, and reassessed |
| Core rehabilitation | 19–50 | Major systems, permitted work, and finishes substantially complete |
| Punch list and listing preparation | 51–60 | Inspections closed, defects corrected, and marketing ready |
| Listing and contract | 61–72 | Property launched and placed under an acceptable contract |
| Buyer closing | 73–90 | Inspection, appraisal, title, financing, and resale completed |
These phases should overlap. Your contractor, insurance agent, title company, and resale agent need to be working before the preceding phase is completely finished.
Days 1–10: Close With a Mobilization Plan
The first ten days should prepare the renovation as well as the acquisition.
During title review, confirm the foreclosure deed, legal description, property taxes, association balances, recorded claims, and the title coverage expected after closing. Verify the exact funds needed for acquisition, repairs, reserves, and immediate property stabilization.
Insurance should reflect the property’s actual vacancy and renovation status. Do not rely on a quotation based on ordinary owner occupancy.
At the same time, finalize the preliminary scope, contractor availability, utility status, permit needs, dumpster arrangements, and long-lead materials. Cabinets, windows, electrical equipment, HVAC components, and specialty fixtures can disrupt the schedule when they are ordered too late.
Set the First Decision Gate
By closing, you should know:
- When you will receive legal possession
- Which repairs can begin immediately
- Which work requires permits or inspections
- What materials must be ordered first
- How much contingency remains available
You may still discover hidden problems after cleanout or demolition. The project should not, however, begin as an undefined renovation.
Days 11–18: Secure, Clean Out, and Reprice the Work
Once you have legal possession, change locks, document the condition, and protect every accessible opening. Depending on the location, you may also need cameras, alarms, exterior lighting, temporary boarding, or regular property checks.
Cleanout should occur early. Abandoned furniture, trash, carpeting, and personal property can conceal water damage, pests, unsafe wiring, damaged flooring, or missing plumbing.
After the property is empty, complete a second contractor walkthrough. Compare actual conditions with the original scope and revise the budget once.
This is the time to recognize concealed work—not halfway through the finish phase.
Utilities also require controlled activation. If pipes, wiring, meters, or mechanical equipment appear damaged, have the appropriate licensed contractor inspect the system before service is restored.
By Day 18, the property should be secure, empty, and supported by a final working scope.
Days 19–50: Sequence the Rehabilitation
Fast renovations depend on trade sequencing rather than simply placing more workers at the property.
Begin with work that prevents continued deterioration. Roof openings, drainage problems, unsafe electrical conditions, active plumbing leaks, structural defects, and unsecured doors should be addressed before cosmetic improvements.
Demolition should expose concealed systems and provide reliable measurements for materials. Plumbing, electrical, HVAC, framing, and other rough work should then follow the required inspection sequence.
The International Code Council’s explanation of the permit and inspection process shows why code review must be part of your schedule rather than treated as paperwork to resolve after construction.
Schedule inspections as soon as the work is ready. A completed trade waiting several days for inspection can hold up drywall, cabinets, flooring, and paint.
Account for Pre-1978 Properties
When renovation disturbs painted surfaces in an older property, confirm whether federal lead rules apply. The EPA’s Lead Renovation, Repair and Painting Program specifically covers qualifying work performed by businesses that buy, renovate, and sell homes for profit.
Use properly certified firms and build lead-safe procedures into the scope and price before work begins.
Standardize the Finish Package
Choose paint, flooring, lighting, hardware, plumbing fixtures, cabinets, counters, and appliances early. A repeatable finish package reduces design delays and makes replacement materials easier to obtain.
By approximately Day 45, major systems should be functioning and finish work should be underway. By Day 50, the remaining tasks should consist mainly of final installations, corrections, cleaning, and inspection closeout.
Days 51–60: Shift From Construction to Sale Preparation
A contractor’s completion notice does not mean the property is ready for buyers.
Complete a detailed punch inspection. Test doors, windows, faucets, drains, appliances, lighting, outlets, HVAC, water pressure, and exterior drainage. Confirm that required permits and inspections are actually closed.
Your resale team should already be updating comparable sales and reviewing active competition. Set the price from the current market rather than the after-repair value projected at acquisition.
Finish deep cleaning, landscaping, staging, photography, disclosures, listing copy, and showing instructions during this phase. Marketing preparation should occur while the final corrections are being completed so the property can launch without another idle week.
Days 61–72: Price for a Contract, Not for Experimentation
A 90-day schedule does not leave room for an inflated listing price followed by several rounds of reductions.
Use current renovated comparables, active competing listings, buyer concessions, and neighborhood-level days on market. National existing-home sales data can provide context, but your listing decision must reflect the immediate local buyer pool.
Establish performance triggers before the listing goes live. Weak showing activity may indicate a price, presentation, access, or marketing problem. Strong showings without offers may indicate that buyers see better value elsewhere.
Do not defend the asking price because the project exceeded budget. Buyers evaluate the finished home against available alternatives, not against your renovation costs.
To finish the full project within 90 days, you will generally need an accepted offer early in this phase and a buyer capable of closing promptly.
Days 73–90: Treat the Buyer Closing as Another Project
A signed contract is a milestone, not the end of the flip.
The buyer may still complete an inspection, obtain insurance, order an appraisal, clear title conditions, negotiate repairs, and satisfy lender requirements. Any one of those steps can delay closing.
Provide permits, invoices, warranties, surveys, title documents, and material information quickly. Prepare accurate comparable-sale support for the appraisal and keep the property secure, clean, insured, and maintained.
Decide how you will handle inspection requests before they arrive. Legitimate safety or functionality problems should be evaluated immediately. For smaller requests, compare the repair cost with the carrying cost and market risk of losing the buyer.
Continue tracking interest, taxes, utilities, insurance, landscaping, and maintenance until the resale funds.
Measure Milestones Instead of Percent Complete
Statements such as “the rehab is 90% finished” can conceal a project that is still waiting for a critical inspection, countertop, electrical panel, or HVAC component.
Track whether each milestone has actually occurred:
- Legal possession and insurance confirmed
- Cleanout and revised scope completed
- Permits issued and materials ordered
- Rough inspections passed
- Major systems operational
- Finish work and punch list completed
- Property photographed and listed
- Buyer under contract
- Resale funded
Assign a responsible person and deadline to each milestone. When one slips, calculate its effect on the phases that follow.
Underwrite More Than 90 Days
Your operating target and financial underwriting should not use the same assumption.
If interest, taxes, insurance, utilities, maintenance, and security cost $4,200 per month, the property costs approximately $140 per day to hold. A 20-day delay consumes another $2,800 before additional contractor visits or buyer concessions.
Run the deal at 90, 120, and 150 days. The shorter timeline should improve your return, but the property should not become unprofitable merely because a permit, material order, or financed buyer extends the schedule.
What the 90-Day Model Really Tests
A successful 90-day foreclosure flip tests your preparation more than your ability to rush.
Title, funding, insurance, contractors, permits, materials, listing strategy, and resale documentation must be arranged before each item becomes urgent. The calendar is lost in the gaps between activities, not only during construction.
Use the 90-day framework for properties where you can control possession, scope, trade sequencing, and marketing. When legal or physical conditions require more time, revise the plan before acquisition.
The objective is not to claim that the flip took exactly three months. It is to move every controllable stage forward without sacrificing due diligence, construction quality, or the margin needed when the schedule changes.
Wondering Where the Savviest Investors Find Their Best Deals?
Access the largest database of foreclosure properties nationwide and discover below-market deals before other investors. Start your search today!
You might also like:
 House Flip Financing Options Compared: Best Ways to Fund Deals
 Finding Contractors for House Flips: The Investor’s Playbook
 Screening Contractors for Flip Projects: Investor Checklist Template
 House Flipping: How to Find, Analyze, Renovate, and Sell a Profitable Flip
 How to Find Land Others Miss: Teardown Lot Split Strategy
 Project Management Software for House Flipping