How City-Owned Properties for Real Estate Investors Work
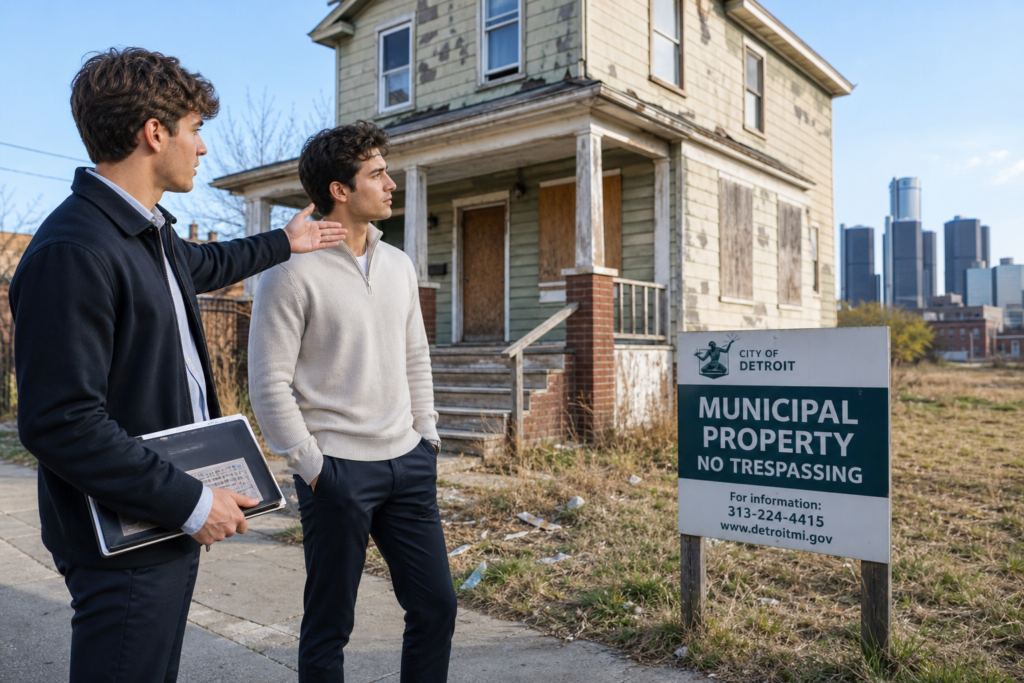
City-owned property investing can give you access to vacant houses, abandoned buildings, infill lots, and surplus parcels that are not marketed like conventional real estate. These properties may have reached municipal ownership through tax foreclosure, code enforcement, demolition proceedings, donation, or an earlier redevelopment effort.
The purchase price can be low, but municipalities usually have objectives beyond completing a sale. The city may want the property rehabilitated, occupied, developed within a set period, or used in a way that supports a neighborhood plan.
You are not merely evaluating a distressed asset. You are evaluating a public disposition process with its own pricing, title, compliance, and redevelopment rules.
Build Your Investing Knowledge One Email at a Time
Foreclosure investing rewards preparation. Join our 2X week newsletter for straightforward guidance on pre-foreclosures, short sales, BRRRR, flipping, and other strategies investors use to evaluate distressed property opportunities.
Municipal Ownership Changes the Acquisition
A private seller is usually focused on price, closing certainty, and timing. A city, county, redevelopment authority, or land bank may evaluate your proposed use, financial capacity, project history, and ability to complete construction.
Some properties are sold at auction to the highest qualified bidder. Others are offered through applications, requests for proposals, sealed bids, or negotiated redevelopment agreements. A city may also reserve certain lots for adjoining owners, affordable housing, community facilities, or business expansion.
This means a cash offer is not always enough. Before underwriting the property, identify which agency owns it and which disposition program applies.
Land Banks Are Not Ordinary Sellers
Land banks are public entities created to return vacant, abandoned, and deteriorated property to productive use. Their powers vary by state, but they may acquire tax-foreclosed property, clear certain title problems, hold land, and transfer it to responsible buyers.
The broader purpose of land-bank property disposition is often community reuse rather than simply obtaining the highest bid. Your proposed project may therefore matter as much as your offer price.
A land bank may request proof of funds, contractor information, a renovation plan, a project schedule, and examples of completed work. If your plan is speculative—such as holding a vacant parcel indefinitely—the application may not fit the program.
The Property May Come With a Performance Obligation
A low municipal sale price may be paired with a requirement to rehabilitate or develop the property within a fixed period.
The deed, purchase agreement, or development agreement may require you to obtain permits, complete exterior work, pass inspections, maintain insurance, remove blight, or secure a certificate of occupancy. The agency may monitor your progress after closing.
Detroit Land Bank auction buyers, for example, are subject to rehabilitation and compliance requirements after purchasing distressed houses. Other jurisdictions use their own deadlines and inspection systems.
You should price those requirements before submitting an offer. A twelve-month completion deadline can become difficult when the property needs zoning relief, utility reconnection, structural engineering, or environmental work.
Failure to comply may produce fines, legal action, or a contractual right for the agency to reclaim the property. The purchase price is therefore only one term of the deal.
Code Liens Need Specific Answers
Municipally controlled properties often have a history of code violations, nuisance complaints, unsafe-structure findings, demolition orders, or unpaid municipal charges.
Do not assume those balances disappear because the city owns or sells the property. Some claims may be waived at closing. Others may remain due, be reduced only after rehabilitation, or require a separate release process.
Ask the agency and title company to identify:
- Which liens and charges will be released before or at closing?
- Which open violations will transfer with the property?
- What work is required to achieve compliance?
- Whether any demolition or unsafe-building order remains active?
Local procedures differ substantially. Miami’s code-enforcement lien process, for example, states that a lien cannot be released while violations remain open or required fees are unpaid.
A municipal sales representative may explain the program, but your title professional should confirm what the deed and public records will actually show.
Houses and Vacant Lots Require Different Analysis
A city-owned house may need cleanout, structural stabilization, roof repair, mechanical replacement, utility activation, and protection against further vandalism. Inspection access may be limited, so you should use a repair range rather than a single optimistic estimate.
A vacant lot appears simpler, but its usability can be harder to establish. Confirm legal access, zoning, setbacks, minimum lot dimensions, utilities, flood exposure, soil conditions, prior demolition, and environmental history.
The parcel may be too narrow for new construction or burdened by easements. A former industrial or commercial site may require environmental testing. A residential lot may need expensive water, sewer, or electrical extensions before it can support development.
You should also determine whether the city restricts the property to a particular use. A discounted lot designated for affordable housing cannot be underwritten as unrestricted market-rate development.
Redevelopment Programs Can Improve the Deal
Municipal acquisition programs sometimes provide benefits that are not available in an ordinary foreclosure purchase.
The agency may consolidate several parcels, resolve portions of the title history, coordinate zoning review, offer technical assistance, or connect approved developers with grants, tax incentives, or low-cost financing. An infill project may also benefit from existing roads, utilities, and neighborhood infrastructure.
Those benefits are not automatic. Funding may be competitive, reimbursement-based, income-restricted, or tied to construction and occupancy milestones.
Evaluate the property both with and without the incentive. If the development works only when an uncertain grant is approved, you do not yet have a financeable deal.
Your Experience Can Affect Eligibility
Some programs distinguish between first-time buyers, homeowners, small developers, and experienced redevelopment firms.
A municipality may limit how many properties you can acquire until you complete the first project. It may also reject applicants with unpaid taxes, unresolved code violations, prior defaults, or incomplete city-owned projects.
If you are entering this market for the first time, choose a project that matches your documented capacity. A modest rehabilitation completed on schedule can help establish a record for larger acquisitions.
Submitting an ambitious proposal without financing, contractors, or relevant experience may prevent approval even when your offer is competitive.
Underwrite the Public Obligations as Project Costs
Assume a city offers a distressed house for $35,000. The apparent discount may look substantial against an estimated renovated value of $180,000.
Your preliminary budget then identifies $75,000 in construction, $12,000 in structural and permit work, $8,000 in utility restoration, $6,000 in security and insurance, and $10,000 in financing and holding costs. The city also requires exterior completion within six months and full occupancy within twelve months.
The opportunity may still work, but it is no longer a simple $35,000 acquisition. You are accepting a capital-intensive project with enforceable deadlines.
Include compliance inspections, surveys, architectural plans, environmental review, title work, and legal documentation in the same analysis as ordinary repair costs.
Decide Whether the Program Fits Your Exit
A municipal property can support a flip, rental, new construction project, or assemblage strategy. The approved use must align with your intended exit.
Review restrictions on resale, owner occupancy, rental rates, tenant income, construction standards, and transfer timing. Some programs prohibit immediate assignments or speculative resales. Others require the city’s approval before you transfer the property.
Do not plan a wholesale or rapid resale exit until you know the agreement permits it. A profitable-looking assignment is irrelevant if the purchase contract cannot be transferred.
A Low Price Is Only One Part of the Offer
Successful city-owned property investing requires you to evaluate the seller’s public objectives along with the property’s physical and financial condition.
Identify the owning agency, disposition method, code liens, title treatment, permitted use, construction deadlines, and remedies for noncompliance. Then determine whether your capital, experience, contractors, and exit strategy match those requirements.
Municipal properties can create opportunities for foreclosure investors who know how to rehabilitate difficult assets and work within a documented redevelopment plan. The strongest acquisition is not necessarily the parcel with the lowest price. It is the one where the public requirements and your investment strategy point toward the same completed project.
Looking for Deeply Discounted Properties Others Don’t Know About?
Don’t miss out on the next great investment opportunity! Search millions of foreclosure listings and get daily alerts for new properties in your target market.